
SBA 7(a) Hotel Acquisition Case Study: Holiday Inn Express & Suites Alice, Texas, Supportable at $5.2 Million Against a $7.6 Million Asking Price
A model feasibility study and going-concern valuation of a listed 70-room select-service hotel under SOP 50 10 8.1 Appendix 15. The case is built on one valuation problem: how the going concern splits between land, building, FF&E and intangible assets. Under the rules in force from 1 October 2026, that split decides whether a Quality of Earnings report is triggered, how much of the loan amortises over ten years, and therefore how much debt the hotel can carry.
By Robert Mitchell, MAI, SRA, AI-GRS, UnionMetric Feasibility | 6 October 2026
Study at a Glance
| Item | Finding |
|---|---|
| Subject | Holiday Inn Express & Suites Alice, 2965 E Main St (State Highway 44), Alice, Texas 78332 |
| Parcel | APN 11020-001-018-00, Block 6, Jim Wells County |
| Improvements | 70 rooms (17 suites, 53 guest rooms), three storeys, interior corridor, built 2004, Formula Blue 2.0 renovation completed 2024 |
| Site and building | 2.13 acres; 46,682 SF gross building area |
| Listed price | $7,600,000 ($108,571 per room) |
| Financing | SBA 7(a), change of ownership, Initial Acquisition under SOP 50 10 8.1 Appendix 15 |
| Market value as is, going concern | $5,200,000 ($74,286 per room) |
| Prospective value upon completion of the change-of-ownership PIP | $5,850,000 ($83,571 per room) |
| Allocation as is | Land $465,000; building and site improvements $4,065,000; FF&E $550,000; intangible assets $120,000 |
| Coverage basis | Historical adjusted EBITDA $587,143 |
| Supportable SBA loan | $4,830,000 at 1.25x historical coverage |
| Borrower equity | $1,282,344, or 21.0% of total project cost |
| Determination | Feasible at $5.2 million; not feasible at the $7.6 million asking price |
Determination
The acquisition of the Holiday Inn Express & Suites Alice is feasible at a purchase price of $5,200,000, the concluded market value of the going concern as is. At that price, a total project cost of $6,112,344 (purchase, change-of-ownership PIP, licence fee, third-party reports, working capital and the SBA guaranty fee) supports an SBA 7(a) loan of $4,830,000. That loan passes the 1.25x historical coverage test on adjusted EBITDA of $587,143, with the real estate share of the loan amortised over 25 years and the FF&E, intangible and working capital share over 10 years, as Appendix 15 is reported to require for the business portion. The buyer contributes $1,282,344, or 21.0 per cent of project cost, more than double the 10 per cent non-reducible minimum.
The acquisition is not feasible at the $7,600,000 asking price. The price exceeds the as-is value by $2.4 million. A 90 per cent loan on the resulting $8.59 million project would need $7.73 million of debt, which breaches the $5 million 7(a) maximum and covers its debt service only 0.80 times. The listing's 8 per cent capitalisation rate is computed on a seller NOI that carries no management fee and no replacement reserve. On a market NOI basis the asking price implies a rate of 7.0 per cent, well below where a tertiary energy and health care market clears.
The two conclusions meet in the equity line. Value sets the most a lender can treat as supported, coverage sets the most debt the hotel can carry, and the difference between the purchase price and the coverage-bound loan is the equity the buyer must bring. At $5.2 million that difference is 21 per cent of the project. At $7.6 million it is 42 per cent of a larger project, and $2.4 million of it buys nothing an appraisal will recognise.
Scope, Basis and Data Verification
This is a model study. UnionMetric was not engaged on this property, did not inspect it, and has no relationship with the seller, the listing broker or any buyer. The subject is a real hotel that was publicly listed for sale as of the effective date, 6 October 2026. It was chosen because its listing record contains the elements this case is meant to teach: a recent brand renovation, a reported NOI, a stated capitalisation rate, a county assessment far below the asking price, and conflicting data across sources. The value indications illustrate method on public data and labelled assumptions. They are not an appraisal, they are not an opinion of market value for any intended user, and they must not be relied on in any transaction involving the property.
The study follows the sequence a lender-grade engagement follows on an SBA change-of-ownership hotel file: market and competitive analysis, a stabilised operating projection, highest and best use, the three approaches to value, reconciliation, the allocation of the going concern into its components, and loan sizing against both value and coverage under SOP 50 10 8.1. The Feasibility Study Methodology Navigator maps the same sequence for other asset classes and programmes.
Every material figure carries a verification status, because a credit reviewer needs to know which numbers can be relied on and which must be replaced before closing.
| Status | Items |
|---|---|
| Primary-verified | U.S. 2025 hotel results and the 2026 to 2027 forecast (CoStar data insights, February and August 2026; CoStar and Tourism Economics release, 6 August 2026); rooms expense ratios from Host Hotels & Resorts SEC filings; the going-concern appraisal allocation rule in the SBA Information Notice issuing SOP 50 10 5(H) |
| Secondary | Listing data (price, NOI, occupancy, ADR, room mix, assessment); competitor room counts and opening years; franchise fee schedule (FDD summaries); every SOP 50 10 8.1 provision (SBA publishes the SOP as a Word document, so provisions are taken from lender-association and practitioner summaries); comparable offerings and sales |
| Not obtained | Jim Wells Central Appraisal District certified values and tax bills; brand-website rates for fixed stay dates; competitor taxes and acreage; local pipeline confirmation from the City of Alice |
| Modelled | Expense ratios, capitalisation and discount rates, PIP scope, interest rate, intangible asset values, FF&E depreciation |
The Valuation Problem This Case Is Built On
A hotel acquisition file carries three numbers that are easy to confuse: the purchase price, the market value of the going concern, and the market value of the real property. Under earlier SBA practice the gap between the last two mattered mainly to the appraiser. Under SOP 50 10 8.1 it becomes a credit variable, because three Appendix 15 provisions, as published summaries report them, read directly off the allocation.
First, the Quality of Earnings requirement applies to Initial Acquisitions where the business purchase price is $3 million or more, and that measure excludes owner-occupied real estate. The split between real estate and everything else therefore decides whether the report is required. Second, the business portion of the loan may not amortise over more than ten years. The larger the share allocated to FF&E and intangible assets, the higher the blended debt constant and the less debt the same EBITDA supports. Third, total transaction debt is capped at the business valuation, with owner-occupied real estate valued separately under Appendix 19, so the allocation sets the support for each piece of the loan.
Method. The allocation is not an accounting step performed after value is set. It is part of the valuation, it must rest on the same evidence, and on an SBA file its credit consequences should be tested before the report is delivered. A going-concern appraisal that concludes on value but allocates by rule of thumb has not finished the assignment.
Project Business Plan
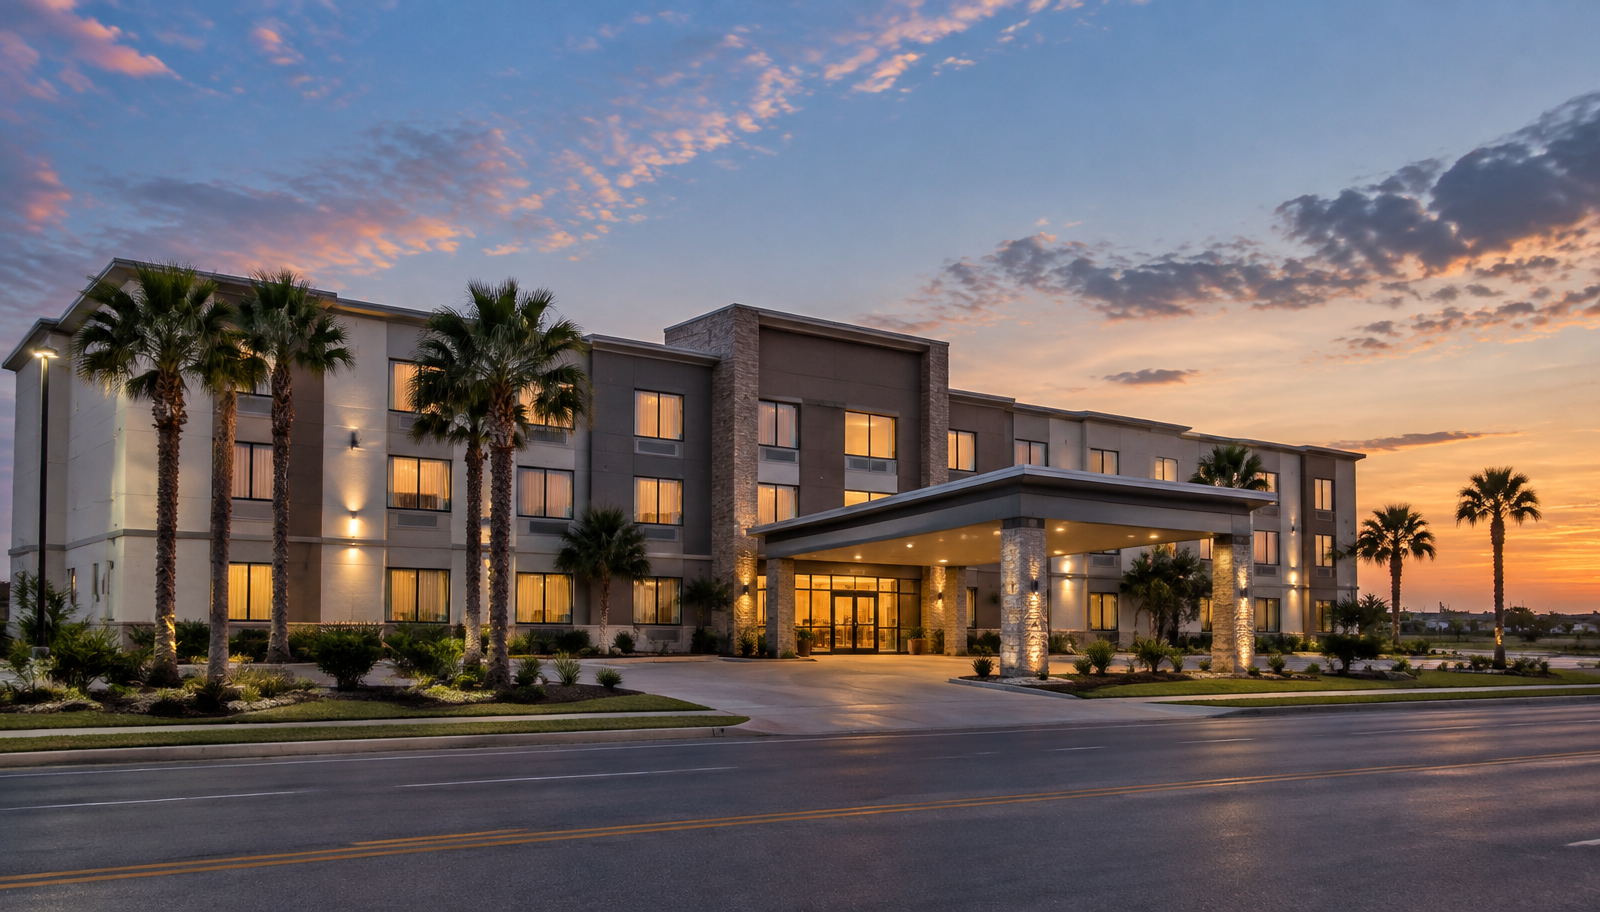
The Project is the acquisition and continued operation of the Holiday Inn Express & Suites Alice, a 70-room upper-midscale select-service hotel operating under an IHG franchise licence at 2965 E Main Street (State Highway 44), near its junction with US Highway 281. The three-storey, interior-corridor building contains 46,682 SF on a 2.13-acre site and offers 17 suites and 53 standard guest rooms at posted rack rates of $163 and $144. The hotel was built in 2004 and completed the brand's Formula Blue 2.0 guestroom and public area renovation in 2024 at a reported cost of about $2 million, or about $28,600 per room. It operates around the clock with front desk, housekeeping, breakfast and maintenance staff of about 22 full-time equivalents (modelled). The buyer acquires the fee simple real estate and the operating business, with the real estate held by an eligible passive company and the hotel operated by the borrowing operating company. The hotel is positioned as the highest-rated branded product on the East Main Street corridor, with an ADR index of 117.1 against its competitive set in the latest disclosed period, and it targets energy and contractor travel, medical and institutional visitors to CHRISTUS Spohn Hospital Alice about 0.8 kilometres away, and transient demand on the US 281 corridor between San Antonio and the Rio Grande Valley.
Marketing & Sales Strategy
The relaunch is timed to the completion of the change-of-ownership PIP, so that the new owner reintroduces a brand-compliant product rather than a hotel under works. The first sales calls go to the hospital's travel and staffing coordinators, home-health and travelling-clinician agencies, and the energy service companies whose crews already stay on the corridor. Distribution is weighted toward the lowest-cost channels: the brand website and app, the loyalty programme, and the global distribution system for corporate accounts, with online travel agencies used to fill shoulder nights rather than to carry the base. Business-to-business outreach covers negotiated local rates for the hospital, contractors, the school district and county offices, and youth and school sports teams travelling through South Texas. The franchise loyalty programme is the built-in acquisition channel: it delivers repeat brand-loyal travellers to the highest-rated branded hotel in a market with no other IHG product.
Amenities
- 70 rooms: 17 suites and 53 standard guest rooms
- Interior corridors on three storeys
- Formula Blue 2.0 guestroom and public area design, completed 2024
- Brand-standard complimentary breakfast
- 2.13-acre site with surface parking at 6.19 spaces per 1,000 SF of building area
- Frontage on State Highway 44 near the US 281 junction, about 0.8 kilometres from CHRISTUS Spohn Hospital Alice
Subject Property: Site, Improvements, Zoning, Utilities and Tax
The site is a 2.13-acre parcel (APN 11020-001-018-00, Block 6) on the East Main Street commercial corridor. The listing reports zoning designation H, under which the hotel operates as an established use, and a parking ratio of 6.19 spaces per 1,000 SF. Public water, sewer and power serve the corridor; capacity and service are confirmed with the City of Alice at engagement. The improvements are a 46,682 SF three-storey interior-corridor building constructed in 2004 and renovated in 2024.
The listing record conflicts with itself, and the conflicts are part of the case.
| Data point | Values found | Treatment |
|---|---|---|
| Room count | 70 (listing, AAA, Travel Weekly); 69 (Crexi); 68 (two booking sites); 65 (Tripadvisor) | 70 used; settled by the franchise licence and the property management system |
| Asking price and rate | $7,600,000 at 8.0% (listing page); $7,350,000 at 7.27% (portal index page) | $7,600,000 tested |
| NOI and stated rate | NOI $640,744 shown beside a 7.84% rate; $640,744 / $7,600,000 = 8.43% | Stated rate does not reconcile; recomputed |
| Last renovation | 2024 (listing); 2018 (one travel trade record) | 2024, supported by the disclosed Formula Blue 2.0 PIP and invoices |
| Market time | Listed 23 November 2024; 472 days on market at a March 2026 portal update | Indicates price resistance |
Method. Conflicting listing data is normal and is not a reason to abandon a subject. The reviewer's question is whether the analyst noticed, chose a figure for a stated reason, and named the document that settles it. Room count is settled by the franchise licence and the property management system, not by the most frequent figure on the web.
The listing's tax panel reports a total assessment of $2,196,692 (land $468,489; improvements $1,728,203) without stating the tax year. That is 29 per cent of the asking price and 42 per cent of the as-is value concluded below. The study carries property taxes of $62,000 for 2025, trended at 3 per cent a year, calculated on the listed assessment at a modelled combined rate of 2.25 per cent plus business personal property tax on the FF&E. Certified values and bills from the Jim Wells Central Appraisal District were not available for this model.
Method. A low assessment flatters the income approach. If a sale prompts the appraisal district to move the assessment toward the allocated value of the real property and FF&E, taxes rise by about $48,500 a year and value falls by about $539,000 at the concluded capitalisation rate. Texas does not require sale prices to be disclosed, and appraisal districts value hotels on their own income models, so the study keeps the current assessment in the base case and states reassessment as a quantified downside. A study that does neither has buried a half-million-dollar assumption.
Market Area and Demand
Alice is the seat of Jim Wells County, at the junction of US Highway 281 and State Highway 44, about 45 miles west of Corpus Christi. Its lodging demand rests on three segments, each with a different trajectory.
Energy is the legacy base. The county has long been described locally as a hub for South Texas oil and gas services, but that base is maturing: county natural gas output reported by DrillingEdge fell from about 2.27 million to about 1.46 million units between 2022 and 2025. Energy crews remain a core weekday segment, and the study projects no growth from them.
Health care is the steadiest segment. CHRISTUS Spohn Hospital Alice sits about 0.8 kilometres from the subject, and local economic development officials have said that health care has overtaken oil field work as the city's leading source of jobs. Travelling clinicians, patient families and vendors generate demand that is less cyclical than energy and well matched to an interior-corridor branded hotel.
Highway transit and leisure complete the mix. The US 281 corridor carries traffic between San Antonio and the Rio Grande Valley, with weekend and event spillover from the Corpus Christi area.
Local public finance is a useful signal. A $10 million city bond failed and city leaders have re-prioritised streets and drainage, while county officials describe sales tax receipts as healthy (KRIS 6, January 2026). The local economy is stable rather than expanding.
National conditions set a ceiling, not a projection. U.S. RevPAR fell 0.3 per cent in 2025, the first decline on record outside a recession, as demand slipped 0.5 per cent. The August 2026 forecast upgrade puts 2026 occupancy at 63.1 per cent with demand up 1.7 per cent, ADR up 3.1 per cent and RevPAR up 4.4 per cent, and 2027 RevPAR up 2.1 per cent. Select-service hotels are expected to finish 2026 at roughly 3.6 per cent RevPAR growth with ADR growth around 2.5 per cent. Much of the 2026 lift came from World Cup host markets, and none of that demand reaches Alice.
Method. National and chain-scale forecasts are the upper bound for a tertiary market, not its base case. The projection here starts from the hotel's own trailing performance and grows ADR at 1.5 per cent in 2026 and 2.0 per cent thereafter, below the select-service forecast and close to expected inflation. In an engagement, the hotel's segmentation report and twelve months of daily performance data replace the listing figures.
Competitive Supply: Competitor Census
The primary competitive set is the branded supply on the East Main Street and US 281 corridors, all within about 1.5 miles of the subject.
Competitor Number 1
Hampton Inn Alice
This 61-room upper-midscale hotel (interior corridor) was opened in 2008 and renovated in 2018. It is located at 3135 E Main St, Alice, TX 78332.
Competitor Number 2
La Quinta Inn & Suites by Wyndham Alice
This 65-room midscale hotel (interior corridor), including 12 suites, was opened in 2008. It is located at 2400 E Main St, Alice, TX 78332.
Competitor Number 3
SureStay by Best Western Alice
This 41-room economy hotel (exterior corridor) operates on US Highway 281 in Alice, TX. Its opening year was not found.
Competitor Number 4
Quality Inn Alice
This midscale hotel operates in Alice, TX. Its room count and opening year were not found.
Real estate taxes and dedicated land for each competitor come from the Jim Wells Central Appraisal District at engagement. Tax per room across the set is the test of whether the subject's tax load is in line with the market or exposed to the reassessment risk described above.
| Hotel | Chain scale | Rooms | Rate evidence (undated) | Source type |
|---|---|---|---|---|
| Subject | Upper midscale | 70 | From $115; rack $144 to $163 | Booking aggregator; listing |
| Hampton Inn Alice | Upper midscale | 61 | From $122.83 | Booking site |
| La Quinta Inn & Suites Alice | Midscale | 65 | From $79; $101 to $125 | Booking aggregators |
| SureStay by Best Western Alice | Economy | 41 | $112 to $157 | Booking aggregator |
| Quality Inn Alice | Midscale | Not found | From $63 | Booking aggregator |
None of these rates comes from a brand website for a fixed stay date, so none enters the projection as fact. They show the order of the market: the subject and the Hampton Inn at the top, La Quinta in the middle, and economy product below.
Method. A rate survey without a stay date and an access date is not evidence. In an engagement the survey pulls one Tuesday and one Saturday about three weeks out from each hotel's own brand website, records the access date, and repeats the pull once to test volatility.
No announced or under-construction hotel was found in Alice. That is a negative search result rather than a confirmed absence, and it is checked with the City of Alice permits office before a study is issued. The cost approach below explains why new supply is unlikely: a new hotel costs far more to build than an existing one is worth. Kingsville hotels (a Holiday Inn Express & Suites, a Hampton Inn, a TownePlace Suites and a La Quinta) and the Corpus Christi northwest and Calallen cluster, 25 to 45 miles away, form a secondary set that competes for leisure and contractor overflow.
Penetration Analysis
The listing disclosed June 2024 RevPAR of $74.53 for the subject against $42.50 for its competitive set, and an ADR index of 117.1.
| Measure | Subject | Competitive set | Index |
|---|---|---|---|
| RevPAR, June 2024 | $74.53 | $42.50 | 175 |
| ADR | Not disclosed | Not disclosed | 117.1 |
| Occupancy (implied from RevPAR and ADR indices) | Not disclosed | Not disclosed | About 150 |
| Share of rooms supply (subject plus three competitors with known counts) | 70 rooms | 237 rooms | Fair share 29.5% |
A RevPAR index of 175 means the subject captured about 1.75 times its fair share of rooms revenue in that month. There are two readings. Either the subject outperforms its market by a wide margin, or the competitive set includes economy product that pulls the average down and flatters the index. Both are probably true. The study does not project any further penetration gain and holds occupancy at the trailing annual level.
Method. Penetration indices only mean something against a defined set and a defined period. A single strong month is not a trend: the June 2024 occupancy of 68.5 per cent compares with 61.48 per cent for the reported annual period. The projection uses the annual figure. A reviewer should ask for the full twelve-month index history before crediting any premium to value.
Occupancy and Average Daily Rate Projection
| Year | Occupancy | ADR | RevPAR | Basis |
|---|---|---|---|---|
| 2025 (modelled trailing) | 61.5% | $112.00 | $68.88 | Listing occupancy 61.48%; 2024 three-month ADR $110.53 trended |
| 2026 | 61.5% | $113.68 | $69.91 | ADR plus 1.5% |
| 2027 (Year 1) | 61.5% | $115.95 | $71.31 | ADR plus 2.0% |
| 2028 | 61.5% | $118.27 | $72.74 | ADR plus 2.0% |
| 2029 | 61.5% | $120.64 | $74.19 | ADR plus 2.0% |
| 2030 | 61.5% | $123.05 | $75.68 | ADR plus 2.0% |
| 2031 | 61.5% | $125.51 | $77.19 | ADR plus 2.0% |
Occupancy is held flat because the subject already captures well above its fair share and the market is not growing. ADR growth sits below the national select-service forecast for every year.
Normalising the Seller's NOI
The listing reports NOI of $640,744. UnionMetric's 2025 model, built from occupancy, ADR and select-service expense ratios, produces income before a management fee and a replacement reserve of $639,238, within 0.3 per cent of the listing figure. The listing NOI is therefore an owner-operator figure. It is the right starting point for the coverage test and the wrong basis for value.
| Measure | Amount | Use |
|---|---|---|
| Listing NOI | $640,744 | Seller's figure; no management fee, no reserve |
| UnionMetric 2025 model, income before management fee and reserve | $639,238 | Reconciles to the listing |
| Less market management charge (3.0% of revenue) | ($53,601) | Owner labour priced at arm's length |
| Historical adjusted EBITDA | $587,143 | Appendix 15 coverage numerator |
| Less reserve for replacement (4.0% of revenue) | ($71,467) | Return of FF&E capital |
| Market NOI, 2025 | $515,676 | Valuation basis; Year 1 projection is $529,318 |
Method. One hotel produces three different "NOI" figures, and each belongs to a different test. The seller's figure supports the asking price. EBITDA after a market management charge is the coverage numerator, because the hotel has to pay someone to run it whether that is a management company or the owner's own time. NOI after the reserve is the valuation basis, because a buyer must replace the FF&E. A capitalisation rate must be applied to the same income definition from which it was extracted. The Quality of Earnings report, with its cash proof tying reported revenue to bank deposits, settles the trailing figure.
Projected Operating Statement, Year 1 (2027)
| Line | Amount | % of revenue | Per room |
|---|---|---|---|
| Rooms revenue | $1,822,008 | 98.5% | $26,029 |
| Other operated revenue | $27,746 | 1.5% | $396 |
| Total revenue | $1,849,754 | 100.0% | $26,425 |
| Rooms expense (24.0% of rooms revenue) | $437,282 | 23.6% | $6,247 |
| Other operated expense | $13,873 | 0.8% | $198 |
| Departmental profit | $1,398,599 | 75.6% | $19,980 |
| Administrative and general | $147,980 | 8.0% | $2,114 |
| Sales and marketing, including loyalty and channel costs | $101,736 | 5.5% | $1,453 |
| Franchise royalty (6% of rooms revenue) | $109,320 | 5.9% | $1,562 |
| Franchise programme fee (3% of rooms revenue) | $54,660 | 3.0% | $781 |
| Franchise technology fee ($17 per room per month) | $14,280 | 0.8% | $204 |
| Repairs and maintenance | $83,239 | 4.5% | $1,189 |
| Utilities | $83,239 | 4.5% | $1,189 |
| Gross operating profit | $804,144 | 43.5% | $11,488 |
| Base management fee (3.0%) | $55,493 | 3.0% | $793 |
| Property taxes | $65,776 | 3.6% | $940 |
| Insurance | $79,568 | 4.3% | $1,137 |
| EBITDA | $603,308 | 32.6% | $8,619 |
| Reserve for replacement (4.0%) | $73,990 | 4.0% | $1,057 |
| Net operating income | $529,318 | 28.6% | $7,562 |
Occupancy 61.5%; ADR $115.95; RevPAR $71.31; 25,550 available room nights.
The franchise lines follow published summaries of the IHG Franchise Disclosure Document: a royalty of 6 per cent of gross rooms revenue, a programme or marketing fee of about 3 per cent from a lower-quality summary, and a technology fee of $17 per room per month. Loyalty, reservation and channel charges are carried in sales and marketing. Items 5 and 6 of the current FDD are read directly in an engagement. Rooms expense at 24.0 per cent of rooms revenue matches the 24.0 to 24.3 per cent reported by Host Hotels & Resorts for 2025, a full-service proxy that brackets the select-service ratio from above. Gross operating profit of 43.5 per cent sits at the lower end of the 44 to 50 per cent limited-service range cited in a 2025 Texas Holiday Inn Express offering. Insurance at $1,137 per room reflects Gulf Coast wind exposure and is modelled.
Highest and Best Use
As though vacant, the site is legally permissible for commercial use under its H designation and the established use pattern of the corridor, and it is physically suitable, with 2.13 acres of frontage on State Highway 44 near US 281. A new hotel is not financially feasible. The April 2026 Holiday Inn Express FDD puts the total investment for a typical 104-room hotel at $133,185 to $200,741 per room excluding land, while an existing, recently renovated branded hotel in this market is worth about $84,000 per room once its PIP is complete. Highway commercial pad uses such as quick-service restaurants, fuel and small-format retail are the feasible uses as vacant, timed to demand. The highest and best use of the site as though vacant is commercial pad development as demand permits.
As improved, the hotel contributes far more than the value of the land it occupies, and no alternative use, conversion or redevelopment competes with continued operation. The highest and best use as improved is continued operation as a branded limited-service hotel.
Method. The as-vacant analysis is not a formality on a hotel acquisition. Here it establishes the barrier to entry that supports the occupancy projection: no developer can build a competing hotel at replacement cost and earn a market return at Alice rates. The same gap reappears in the cost approach as external obsolescence.
Cost Approach
| Component | Amount |
|---|---|
| Replacement cost new, building and site improvements ($110,000 per room) | $7,700,000 |
| Entrepreneurial incentive (10%) | $770,000 |
| Replacement cost new including incentive | $8,470,000 |
| Less physical depreciation (effective age 12 years of a 50-year life, 24%) | ($2,032,800) |
| Depreciated improvements | $6,437,200 |
| Plus land (2.13 acres at about $5.00 per SF) | $465,000 |
| Real property indication before external obsolescence | $6,902,200 |
| Plus FF&E and intangible assets upon PIP completion | $820,000 |
| Going-concern indication before external obsolescence | $7,722,200 |
| External obsolescence extracted from the reconciled value | ($1,872,200) |
| Reconciled prospective value upon PIP completion | $5,850,000 |
Replacement cost is derived from the FDD range, stripped of FF&E, franchise and pre-opening costs and working capital, and scaled to a 70-room building in South Texas. The land value of about $5.00 per SF is corroborated by the listed land assessment of $468,489; land sales are collected at engagement. The 2004 prototype carries some functional dated design, but the 2024 renovation cured the visible items and no separate functional deduction is taken. External obsolescence of $1.87 million, 22 per cent of replacement cost including incentive, is extracted from the income and sales approaches rather than measured on its own.
Method. External obsolescence can be measured independently only through paired sales or by capitalising a rate shortfall against a market where rates support new construction. Neither is available for Alice. When obsolescence has to be extracted from the other approaches, the cost approach cannot carry weight in the reconciliation. It still does two jobs: it is the ceiling no informed buyer would exceed, and the size of the obsolescence measures how far the market is from supporting new competition.
Sales Comparison Approach
Texas is a non-disclosure state, so county deed records do not show sale prices. Evidence comes from press releases, trade coverage and offerings. Three of the four comparables below are offerings rather than closed sales, which is a weakness stated plainly. A courtroom auction of a 122-room Hampton Inn & Suites in Sugar Land in November 2025 closed at 117 per cent of its opening bid, but the price was not disclosed.
Each price is first restated in brand-compliant condition by adding back the PIP the buyer would inherit, so that every comparable is compared on the same footing; the subject's own PIP is deducted at the end. Offerings carry a modelled listing-to-sale adjustment of minus 7 per cent.
| Comparable | Status | Rooms | Price per room | PIP add-back | Listing | Location and market | Size | Adjusted per room |
|---|---|---|---|---|---|---|---|---|
| Holiday Inn Express & Suites Florida City, FL | Closed, February 2025 | 105 | $125,714 | Not disclosed | None | -30% | None | $88,000 |
| Holiday Inn Express & Suites Texas City, TX | Offered, 2025 | 72 | $86,806 | +$2,500 | -7% | -5% | None | $78,901 |
| Holiday Inn Express & Suites Houston NW Cypress, TX | Offered, 2026 | 125 | $92,800 | Not disclosed | -7% | -10% | +3% | $80,003 |
| Holiday Inn Express & Suites Cuero, TX | Offered, 2025 | 78 | About $59,000 | +$20,513 | -7% | +5% | None | $77,643 |
Adjusted prices range from $77,643 to $88,000 per room. The most weight goes to Florida City, the only closed price, and to Texas City, the closest regional and physical match. The concluded value is $83,000 per room in brand-compliant condition, or $5,810,000, rounded to $5,800,000.
The rooms revenue multiplier is a cross-check. The Texas offerings ask 3.0 to 4.0 times rooms revenue before any listing adjustment, and Florida City closed at 6.33 times in a South Florida gateway market. At 3.2 times the subject's Year 1 rooms revenue of $1,822,008, the indication is $5,830,000.
Method. A rooms revenue multiplier ignores margin. Cuero's 3.0 times reflects a hotel reporting a 21.6 per cent GOP and a $20,000-per-room PIP; the subject's modelled GOP is 43.5 per cent after a 2024 renovation. Two hotels at the same multiplier can be worth very different amounts, which is why the multiplier is a cross-check and never the conclusion.
Income Capitalisation Approach
The capitalisation rate is built from four tests.
| Test | Inputs | Indicated rate |
|---|---|---|
| Band of investment | 65% loan at 7.50% over 25 years (constant 8.87%); 35% equity at a 10.0% dividend rate | 9.26% |
| Debt coverage (lender floor) | 1.25 x 0.65 x 8.87% | 7.21% |
| Asking price, restated | Year 1 market NOI / $7,600,000 | 6.96% |
| Texas offerings | 3.0x to 4.0x rooms revenue at the subject's 29.1% NOI-to-rooms-revenue margin | 7.3% to 9.7% |
The asking evidence sits at the bottom of the range because listings reflect seller expectations. The debt coverage figure is a floor rather than a market rate. The band of investment and the upper half of the offering range describe where a tertiary, energy-exposed market clears. The concluded overall rate is 9.00 per cent.
Direct capitalisation: Year 1 NOI of $529,318 divided by 9.00 per cent indicates $5,881,300, rounded to $5,880,000.
A ten-year discounted cash flow tests the direct capitalisation. NOI grows from $529,318 in Year 1 to $619,428 in Year 10. The reversion capitalises Year 11 NOI of $630,206 at a terminal rate of 9.50 per cent, less 3 per cent selling costs, for $6,434,700. At a 10.75 per cent discount rate the cash flows are worth $3,363,800 and the reversion $2,317,900, for a total of $5,681,700, rounded to $5,680,000.
The income approach concludes at $5,850,000, weighted to direct capitalisation because the hotel is already stabilised, with the discounted cash flow confirming the range.
Method. The 9.00 per cent rate is applied to NOI after a market management fee, all franchise costs and a 4 per cent reserve. Applied to the seller's $640,744, the same rate would produce $7.1 million, which is how a $7.6 million asking price can look almost reasonable on a listing page. Matching the rate to the income definition is the single most common correction a reviewer makes on a hotel file.
Reconciliation of Value
| Approach | Indication | Role in the conclusion |
|---|---|---|
| Income capitalisation | $5,850,000 | Primary |
| Sales comparison | $5,800,000 | Supporting |
| Cost, before external obsolescence | $7,722,200 | Ceiling and feasibility signal only |
| Prospective value upon PIP completion | $5,850,000 | Concluded |
The prospective value is the value of the going concern once the change-of-ownership PIP is complete and the new licence is issued. The as-is value deducts the cost of getting there.
| Step | Amount |
|---|---|
| Prospective value upon completion of the change-of-ownership PIP | $5,850,000 |
| Less change-of-ownership PIP (modelled at $7,500 per room) | ($525,000) |
| Less IHG licence application fee | ($50,000) |
| Less income displaced during the PIP works | ($25,000) |
| Less entrepreneurial incentive on the PIP (about 10%) | ($50,000) |
| Market value as is, going concern | $5,200,000 |
Allocating the Going Concern: Land, Building, FF&E and Intangible Assets
SBA's requirement is long-standing. The Information Notice issuing SOP 50 10 5(H) required that a going-concern appraisal of a special-purpose property, naming hotels among the examples, be performed by a Certified General Real Property Appraiser experienced in the property type, that it allocate separate values to land, building, equipment and intangible assets, and that the appraiser have completed at least four going-concern appraisals of equivalent property in the prior 36 months. Published summaries report that the allocation requirement carries forward into SOP 50 10 8.1.
The method for separating the business from the real property is not settled. The Appraisal Institute has not endorsed a single approach, and four methods are in use.
| Method | How it isolates the business | Where it has been tested |
|---|---|---|
| Fee deduction (the Rushmore approach) | Deducts management and franchise fees as operating expenses and a reserve for FF&E; the capitalised remainder is real property plus FF&E | Adopted in Chesapeake Hotel LP v. Township of Teaneck (N.J. Tax Ct., 1989); held insufficient under California law in SHC Half Moon Bay, LLC v. County of San Mateo (2014) |
| Business enterprise approach | Also deducts a return on FF&E, start-up costs, the value of the flag and residual goodwill | Favoured by property owners seeking lower real property assessments |
| Residual or excess earnings | Deducts market returns on land, building and FF&E; the remaining income is intangible | A Summer 2016 Appraisal Journal example allocated $72,608 per room to business value |
| Capitalised fees | Capitalises the management and franchise fees as business value | Rejected as double counting when combined with a net revenue loss method (Utah State Tax Commission, March 2023) |
The study applies them as follows. FF&E is valued at depreciated replacement cost: the 2024 package at $12,500 per room new ($875,000), about 37 per cent depreciated on a seven-year life, gives $550,000 as is, and the $100,000 of FF&E replaced under the PIP brings it to $650,000. The intangible assets that transfer are the assembled workforce (22 positions at about $3,500 each to recruit and train, or $77,000) and the in-place operating systems, local accounts and advance bookings ($43,000), for $120,000 as is. The franchise licence does not transfer with a sale; the buyer applies for a new one, and its $50,000 fee becomes an intangible asset once the licence is issued, for $170,000 upon PIP completion. The residual test then decides whether any goodwill remains. The cost approach puts the real property at $6.90 million before external obsolescence, well above the $5.03 million left for real property after FF&E and intangibles are deducted from the prospective value. The residual for goodwill is negative, so there is none.
| Component | As is | Share | Upon PIP completion | Share |
|---|---|---|---|---|
| Land | $465,000 | 8.9% | $465,000 | 7.9% |
| Building and site improvements | $4,065,000 | 78.2% | $4,565,000 | 78.0% |
| FF&E | $550,000 | 10.6% | $650,000 | 11.1% |
| Intangible assets | $120,000 | 2.3% | $170,000 | 2.9% |
| Total going concern | $5,200,000 | 100.0% | $5,850,000 | 100.0% |
A capitalised-fee allocation would instead assign the Year 1 management fee and franchise costs, $55,493 plus $178,261, capitalised at 9.00 per cent, or $2,597,300, to intangible assets. The next section shows what that does to the credit file.
Method. The finding worth carrying to other files is this. The fee-deduction and business enterprise approaches diverge most where a hotel earns more than its tangible assets would justify, typically in high-barrier markets where replacement cost sits below value. In a tertiary market where value sits well below replacement cost, the residual for goodwill is negative and both approaches converge on a small intangible made up of start-up elements. The method dispute is real, but its size depends on the market.
The Change-of-Ownership PIP: As-Is Versus As-Renovated Value
IHG normally inspects a hotel and issues a property improvement plan when it changes hands. The completed Formula Blue 2.0 renovation lowers that risk without removing it. The study models $7,500 per room, or $525,000, within a range of $5,000 to $10,000 per room ($350,000 to $700,000). The evidence brackets the range: a non-renovated Holiday Inn Express in Cuero disclosed an estimated change-of-ownership PIP of about $1.6 million, or $20,000 per room, while recently renovated Holiday Inn Express hotels offered in Texas City and Columbus, Texas expected minimal or minor PIPs.
This PIP preserves income rather than raising it. Its purpose is to secure the licence on which the hotel's rate premium depends, so the study projects no uplift and treats the full cost, plus displaced income and an incentive for managing the works, as a cost to cure deducted from the prospective value. A repositioning PIP that moved the hotel up the rate scale would be valued differently: the as-renovated value would carry the projected uplift, and the as-is value would deduct cost and incentive from that higher figure.
The PIP is financed as a renovation use of proceeds, held in escrow and released against completed work, which is common lender practice. The published summaries of SOP 50 10 8.1 do not address PIP funds, so the use-of-proceeds and disbursement provisions of the 1 October 2026 text are read before commitment.
Method. Two values need two dates. The as-is value is effective on the date of the report. The value upon PIP completion is a prospective opinion, effective on the expected completion date and labelled as such, as USPAP requires for any value opinion as of a future date. A report that blends the two, or labels the as-renovated figure as current, misstates the collateral on the day the loan closes.
SBA Programme Compliance Under SOP 50 10 8.1
| Test | Requirement as reported | This file | Result |
|---|---|---|---|
| Category | Initial Acquisition is the default for a buyer without a same-industry business | New owner with no affiliated hotel | Initial Acquisition |
| Historical coverage | At least 1.25x on the last fiscal year or the two-year average, historical or adjusted EBITDA over combined post-transaction debt service; projections may not be relied on; non-standby interest-only debt imputed at a 10-year amortisation | $587,143 / $469,579 | 1.25x, passes |
| Equity | At least 10%, non-reducible; standby and seller debt may supply no more than half of the required injection | 21.0% cash | Passes |
| Quality of Earnings | Required where the business purchase price is $3 million or more, measured before financing and excluding owner-occupied real estate; commissioned by the lender with a cash proof | $670,000 business purchase price under the concluded allocation | Not triggered on the measure; ordered anyway |
| Business portion amortisation | No longer than 10 years | FF&E, intangibles, licence, QoE and working capital on 10 years | Modelled |
| Debt cap | Total debt capped at the business valuation; owner-occupied real estate valued separately | $4,830,000 against a $5,200,000 as-is value | Passes |
| Loan maximum | $5,000,000 individual 7(a) maximum | $4,830,000 | Passes |
| 7(a) Small | Not available for a change of ownership | Standard 7(a) | Complies |
| Going-concern appraisal | Certified General appraiser with special-purpose experience; allocation to land, building, equipment and intangibles | Allocation in this study | Required at engagement |
SBA issued SOP 50 10 8.1 with Information Notice 5000-880695 on 14 August 2026, then issued technical updates under Information Notice 5000-882227 on 25 September 2026, effective 1 October 2026. The National Association of Government Guaranteed Lenders reported that the updated version supersedes the August text, which never took effect. Every provision above is read against the 1 October text before a commitment issues. The SBA feasibility study page sets out how the study fits the wider 7(a) credit file.
The $3 Million QoE Line and the Allocation
The same hotel, with the same EBITDA, supports very different loans depending on how the going concern is allocated and how the loan amortises.
| Allocation basis | Business purchase price for the QoE test | QoE required by the measure | Share amortised over 25 years | Blended debt constant | Loan supported at 1.25x |
|---|---|---|---|---|---|
| Concluded (fee deduction with in-place intangibles) | $670,000 | No | 84.1% | 9.72% | $4,830,000 |
| Capitalised management and franchise fees | $3,147,300 | Yes | 42.7% | 11.95% | $3,930,800 |
| Hotel real estate not treated as excluded owner-occupied real estate | $5,200,000 | Yes | 84.1% | 9.72% | $4,830,000 |
| Reference: whole loan over 25 years, as under SOP 50 10 8 practice | Not applicable | Not applicable | 100.0% | 8.87% | $5,296,800 |
| Reference: whole loan over 10 years | Not applicable | Not applicable | 0.0% | 14.24% | $3,297,600 |
Under the concluded allocation the business purchase price is $670,000, well under the $3 million line. A capitalised-fee allocation moves it to $3.15 million, triggers the report, shifts more than half of the loan onto a ten-year schedule and removes $899,200 of debt capacity. The open question is definitional: whether a hotel's real estate counts as excluded owner-occupied real estate for the QoE measure. The published summaries do not say, and if it does not, the report is required at any price above $3 million. The study recommends a lender-ordered QoE in every case and includes its cost in the budget. The SBA Acquisition Report Stack Planner runs this test on any change-of-ownership file.
Method. Under the old rules an aggressive intangible allocation was mainly a property tax argument. Under 8.1 the same allocation, placed in an SBA file, can trigger a third-party report, move debt onto a ten-year schedule and cost the buyer nearly $900,000 of borrowing. The appraiser's method choice has to be defensible on the evidence, and the lender's reviewer should test the allocation against the income approach before accepting it.
Project Cost Estimate and Loan Assumptions
Location: 2965 E Main St, Alice, TX 78332 | Rooms: 70 | Size in SF (Gross): 46,682
| Item | Cost | Cost in % | Cost per SF |
|---|---|---|---|
| Acquisition | |||
| Land | $465,000 | 7.6% | $9.96 |
| Building and Site Improvements | $4,065,000 | 66.5% | $87.08 |
| FF&E in Place (depreciated) | $550,000 | 9.0% | $11.78 |
| In-Place Intangible Assets | $120,000 | 2.0% | $2.57 |
| Total Acquisition | $5,200,000 | 85.1% | $111.39 |
| Renovation | |||
| Change-of-Ownership PIP, Real Property Items | $425,000 | 7.0% | $9.10 |
| Change-of-Ownership PIP, FF&E Items | $100,000 | 1.6% | $2.14 |
| Total Renovation | $525,000 | 8.6% | $11.25 |
| Soft Cost | |||
| IHG Licence Application Fee | $50,000 | 0.8% | $1.07 |
| Quality of Earnings Report | $30,000 | 0.5% | $0.64 |
| Appraisal and Appraisal Review | $15,000 | 0.2% | $0.32 |
| Phase I Environmental Site Assessment | $4,000 | 0.1% | $0.09 |
| Legal, Title and Closing | $55,000 | 0.9% | $1.18 |
| Total Soft Cost | $154,000 | 2.5% | $3.30 |
| Financial Cost | |||
| Working Capital Reserve | $100,000 | 1.6% | $2.14 |
| SBA Guaranty Fee (modelled) | $133,344 | 2.2% | $2.86 |
| Total Financial Cost | $233,344 | 3.8% | $5.00 |
| Total Subject Project Cost | $6,112,344 | 100.0% | $130.94 |
Source: Listing data, IHG FDD summaries, UnionMetric
| Loan Assumptions | |
|---|---|
| LTC Ratio | 79.0% |
| Loan | $4,830,000 |
| Equity | $1,282,344 |
| Interest Rate | 7.50% (modelled) |
| Amortisation | 25 years on the real estate share (84.1%); 10 years on the business share (15.9%); blended constant 9.72% |
| Annual Debt Service | $469,579 |
The total project cost is $87,319 per room. The guaranty fee is modelled on a 75 per cent guarantee using the fee structure for loans above $1 million and is confirmed against the current fiscal year notice at commitment.
Five-Year Pro Forma and Debt Service Coverage
| Year | Occupancy | ADR | RevPAR | Total revenue | GOP | EBITDA | Debt service | DSCR |
|---|---|---|---|---|---|---|---|---|
| 2027 | 61.5% | $115.95 | $71.31 | $1,849,754 | $804,144 | $578,308 | $469,579 | 1.23x |
| 2028 | 61.5% | $118.27 | $72.74 | $1,886,749 | $820,512 | $614,206 | $469,579 | 1.31x |
| 2029 | 61.5% | $120.64 | $74.19 | $1,924,484 | $837,208 | $625,279 | $469,579 | 1.33x |
| 2030 | 61.5% | $123.05 | $75.68 | $1,962,974 | $854,238 | $636,528 | $469,579 | 1.36x |
| 2031 | 61.5% | $125.51 | $77.19 | $2,002,233 | $871,608 | $647,956 | $469,579 | 1.38x |
Year 1 EBITDA is shown after $25,000 of income displaced during the PIP works, which the working capital reserve covers. Projected coverage is not the Appendix 15 test, which is historical; it shows how coverage develops after closing.
Break-Even Analysis
Break-even is calculated with a fixed and variable split rather than flat expense ratios: 35 per cent of rooms expense, 75 per cent of administrative and general, 50 per cent of sales and marketing and 60 per cent of repairs, maintenance and utilities are treated as fixed; franchise and management fees are fully variable; taxes and insurance are fixed.
| Measure | Break-even | Year 1 base | Margin |
|---|---|---|---|
| Occupancy for 1.00x coverage at Year 1 ADR | 54.5% | 61.5% | 7.0 points |
| Occupancy for 1.25x coverage | 60.6% | 61.5% | 0.9 points |
| ADR for 1.00x coverage at 61.5% occupancy | $105.58 | $115.95 | 8.9% |
| ADR for 1.25x coverage | $114.69 | $115.95 | 1.1% |
| Occupancy at which EBITDA is zero | 30.0% | 61.5% | 31.5 points |
The loan is sized to coverage, so the headroom to 1.25x is thin by construction. The real protection is the 7.0 points of occupancy, or 8.9 per cent of ADR, between the base case and the point at which the hotel stops covering its debt.
Method. Flat expense ratios make a hotel look safer than it is, because they let costs fall in step with revenue. Rooms labour, administration and maintenance do not fall that way in practice. A break-even built on a fixed and variable split is the version a credit committee should see.
Sensitivity Analysis
| Scenario (Year 1) | Occupancy | ADR | EBITDA | DSCR | Value at 9.00% |
|---|---|---|---|---|---|
| Base | 61.5% | $115.95 | $603,308 | 1.28x | $5,881,300 |
| Occupancy minus 3 points | 58.5% | $115.95 | $545,858 | 1.16x | $5,283,100 |
| Occupancy plus 3 points | 64.5% | $115.95 | $660,758 | 1.41x | $6,479,500 |
| ADR minus 5% | 61.5% | $110.16 | $528,545 | 1.13x | $5,091,700 |
| ADR plus 5% | 61.5% | $121.75 | $678,070 | 1.44x | $6,670,900 |
| Occupancy minus 3 points and ADR minus 5% | 58.5% | $110.16 | $474,743 | 1.01x | $4,532,000 |
| Energy downturn: occupancy minus 6 points, ADR minus 8% | 55.5% | $106.68 | $380,459 | 0.81x | $3,544,800 |
| Other variable | Change | Effect |
|---|---|---|
| Capitalisation rate | 8.50% / 9.50% | Value $6,227,300 / $5,571,800 |
| Interest rate | 8.50% | Blended constant 10.49%; DSCR 1.16x on the $4.83 million loan; supportable loan $4,477,100 |
| Interest rate | 9.50% | Blended constant 11.29%; DSCR 1.08x; supportable loan $4,162,000 |
| Property tax reassessment to the allocated real property and FF&E | Taxes up about $48,500 a year | Value down about $539,200 |
A 7(a) loan of this size is normally variable-rate. A 100 basis point rise removes about $354,000 of debt capacity and cuts coverage by about as much as a 3-point fall in occupancy. The energy downturn case is the one that matters for this market: a return to the conditions that thinned county gas output would push coverage below 1.00x.
Loan Sizing: Value Versus Coverage
| Constraint | Maximum loan |
|---|---|
| 90% of total project cost ($6,112,344) | $5,501,100 |
| Individual 7(a) maximum | $5,000,000 |
| Debt capped at the as-is going-concern value | $5,200,000 |
| 1.25x historical coverage with blended amortisation | $4,830,000 |
Coverage binds, not value. Under the earlier practice of amortising a real-estate-heavy hotel loan over 25 years in full, the same EBITDA would have supported $5.30 million and the value cap would have been close to binding. The ten-year business portion lifts the blended constant from 8.87 to 9.72 per cent, and that difference, not the appraisal, sets the loan. That is the general pattern for hotel acquisitions under 8.1, and it is why the allocation now matters to the credit officer as much as to the appraiser.
Where the Feasibility Conclusion and the Value Conclusion Meet
The valuation says the going concern is worth $5.2 million today and $5.85 million once the PIP is complete. The feasibility analysis says the hotel's verified trailing earnings carry $4.83 million of debt at 1.25 times under the 8.1 amortisation rules. The allocation joins the two: it decides which share of the loan runs over 25 years, whether the QoE line is crossed, and therefore how much of the value can be borrowed. At $5.2 million the buyer funds 21 per cent of the project and the file passes every test. At $7.6 million the buyer funds 42 per cent of a larger project, and $2.4 million of that equity pays for income the hotel does not produce at market costs. The determination is that the acquisition is feasible at $5.2 million and not feasible at the asking price.
Risk Factors
Energy concentration is the first risk. Jim Wells County gas output has fallen by about a third since 2022, and a further downturn in field activity would remove weekday demand faster than health care could replace it.
The record is old. Most listing performance data dates from mid-2024, and the coverage test depends on trailing results that only a Quality of Earnings report can confirm.
The PIP scope is unknown until IHG inspects. The study models $525,000; a scope closer to the Cuero figure would add about $875,000 and reduce the as-is value by more than that once displacement and incentive are added.
The rules are new. Every SOP 50 10 8.1 provision used here comes from published summaries of a text that was revised before it took effect.
Property tax is exposed. Reassessment toward the allocated value would cut value by about $539,000.
Insurance is volatile. Gulf Coast wind cover is a large fixed cost and has risen faster than revenue across the region.
The interest rate floats. A variable-rate 7(a) loan loses about $354,000 of capacity for each 100 basis point rise.
The licence is not automatic. IHG must approve the buyer and issue a new licence, and the deal depends on it.
Conditions and Limitations
This is a model study prepared to illustrate feasibility and valuation method on a publicly listed property. It is not an appraisal, it was not prepared under an engagement, it was not prepared for any intended user other than the readers of this site, and no one should rely on it for any decision about the property. UnionMetric did not inspect the property, review its books, or communicate with its owner, broker or franchisor.
The study relies on the following extraordinary assumptions: that the listing's reported NOI, occupancy, ADR, room mix and assessment are accurate for the periods stated; that the hotel contains 70 rooms; that the change-of-ownership PIP will cost about $525,000; and that the SOP 50 10 8.1 provisions apply as summarised in the cited secondary sources. If any proves false, the conclusions may change. The prospective value upon PIP completion rests on the hypothetical condition that the PIP is complete and a new IHG licence has been issued as of that date. Expense ratios, capitalisation and discount rates, the interest rate, the PIP budget, intangible asset values and FF&E depreciation are UnionMetric assumptions. Figures are rounded, and totals may differ slightly from the sum of their parts.
What the Lender Received
In an engagement on this file, the lender would receive:
- A market and competitive analysis with a dated brand-website rate survey, an annual penetration history and a pipeline check with the City of Alice
- A stabilised operating projection reconciled line by line to the Quality of Earnings report
- A going-concern appraisal by a Certified General appraiser with hotel going-concern experience, developing all three approaches and reporting as-is and prospective values with their effective dates
- An allocation schedule for land, building, FF&E and intangible assets, with the method, the residual test and the effect on the QoE line documented
- The Appendix 15 coverage test on QoE-adjusted EBITDA under the blended amortisation, and the loan sizing against value, coverage and the 7(a) maximum
- Break-even and sensitivity analysis on a fixed and variable expense split, including interest rate and reassessment cases
- A data verification register separating primary-verified, secondary and modelled figures
To discuss a hotel acquisition or any other change-of-ownership file, request a feasibility study.
Sources
- 2965 E Main St, Alice, TX 78332: Holiday Inn Express & Suites Alice, listing, Crexi, updated 6 March 2026
- 2965 E Main St, Alice, TX 78332: Holiday Inn Express & Suites Alice, listing, LoopNet, viewed October 2026
- Hotels for Sale, index page 3, LoopNet, viewed October 2026
- Holiday Inn Express, Alice, TX, property record, Travel Weekly, 2026
- Holiday Inn Express & Suites Alice by IHG, property page, Tripadvisor, 2026
- Holiday Inn Express & Suites Alice, property page, Hotels.com, 2026
- Holiday Inn Express & Suites Alice, property page, Reservations.com, 2026
- Holiday Inn Express & Suites Alice, TripCanvas property page, AAA, 2026
- Hampton Inn Alice, property page, Hilton, 2026
- Hampton Inn Alice, property record, Travel Weekly, 2026
- La Quinta Inn & Suites Alice, property record, Travel Weekly, 2026
- Hampton Inn Alice, 3135 East Main, property page, HotelPlanner, 2026
- Alice hotels list, Trip.com, 2026
- The Best Alice Hotels, Booking.com, 2026
- SureStay by Best Western Alice, Momondo, 2026
- Holiday Inn Express & Suites Alice by IHG, Momondo, 2026
- Hotels in Alice, Texas, Tripadvisor, 2026
- Oil and Gas Production in Jim Wells County, TX, DrillingEdge, 2025
- Alice health care employment report, KIII-TV 3News, undated
- Jim Wells County sets 2026 priorities on growth, infrastructure, KRIS 6 News, January 2026
- U.S. Hotel Forecast Assumptions, February 2026, CoStar data insights blog, February 2026
- CoStar and Tourism Economics upgrade U.S. hotel growth forecast, press release, CoStar, 6 August 2026
- U.S. Hotel Forecast Assumptions, August 2026, CoStar data insights blog, August 2026
- Host Hotels & Resorts, Inc., Form 10-Q for the quarters ended 31 March 2025 and 30 June 2025, U.S. Securities and Exchange Commission
- Host Hotels & Resorts, Inc., Form 10-K for fiscal year 2025, U.S. Securities and Exchange Commission
- Holiday Inn Express franchise profile, Entrepreneur, 2026
- Holiday Inn and Holiday Inn Express Franchise Opportunities, FranchiseHelp, 2026
- Holiday Inn Express Franchise Disclosure Document, April 2026, summary, Franchise Disclosure Documents, 2026
- Holiday Inn Express & Suites Cuero, TX Listed for Sale, Hotel News Resource, 2025
- 65 Key Holiday Inn Express & Suites Columbus, Texas Offered for Sale, Hotel News Resource
- Holiday Inn Express & Suites Texas City, offering page, 2025
- Houston-Area Holiday Inn Express Listed at $11.6 Million as Cypress Corridor Expands, Hotel News Resource, 2026
- Holiday Inn Express & Suites Houston East Baytown Hotel Listed for Sale, Hotel News Resource, 2023
- Royal Hotel Group acquires Hampton Inn & Suites by Hilton in Texas, Hotel Management Network, November 2025
- Kabani Hotel Group closes $13.2M sale of Florida Holiday Inn, Hotel Management, February 2025
- Kabani Hotel Group Announces Sale of Holiday Inn Express & Suites Florida City, Lodging Magazine, February 2025
- FF&E specification for hospitality projects: cost per key, durability standards and the five-phase process, DataDrivenAEC, 2026
- Hotel FF&E Budget Breakdown: What's Actually Included, Jadeant, 2026
- Information Notice 5000-1340, Issuance of SOP 50 10 5(H), U.S. Small Business Administration
- Two Major SBA Announcements: Issuance of SOP 50 10 8.1 and a New Expansion of the ITL Program, National Association of Government Guaranteed Lenders, August 2026
- SOP Update: SBA Publishes SOP 50 10 8.1 with Technical Policy Updates, National Association of Government Guaranteed Lenders, September 2026
- Information Notice 5000-882227, Issuance of Technical Updates to SOP 50 10 8.1, U.S. Small Business Administration, 25 September 2026
- SOP 50 10, Lender and Development Company Loan Programs, U.S. Small Business Administration, 2026
- SBA Acquisitions After October 1, 2026: Four Deal Boxes, 1.25x Coverage, and the $3 Million Quality of Earnings Rule, OpsFi, 16 August 2026
- SBA Expansion Acquisition Rules 2026: SOP 50 10 8.1 vs 50 10 8, Pioneer Capital Advisory, 2026
- New SOP Changes SOP 50 10 8.1, Searchfunder, 2026
- Chesapeake Hotel LP v. Township of Teaneck, New Jersey Tax Court, 1989
- SHC Half Moon Bay, LLC v. County of San Mateo (2014) 226 Cal.App.4th 471, California Court of Appeal, 22 May 2014
- Utah State Tax Commission, Appeal Nos. 20-710, 20-711, 20-713, 20-714 and 20-718, Property Tax, Tax Year 2019, decisions signed 30 March 2023
- The Appraisal Journal, Summer 2016, Appraisal Institute
- Hotel Market Analysis and Valuation, Appraisal Institute, 2012
- The Dictionary of Real Estate Appraisal, 5th edition, Appraisal Institute
- Hotel Valuation and the Appraisal Institute, 2014 Hospitality Summit session materials, 2014
- Intangible Assets in Hotel Property Tax Assessments, Hotel News Resource
- Uniform Standards of Professional Appraisal Practice, 2024 edition, The Appraisal Foundation
Related services and regulatory reading
- 2026 Feasibility Methodology Atlas
- Hotel feasibility study
- Hotel engagement hub
- SBA 7(a) engagements
- SBA feasibility study
- SOP 50 10 8.1 report stack
- SBA Acquisition Report Stack Planner
- Feasibility Study Methodology for SBA and USDA Loans: The Valuation and Market Analysis Methods a Consultant Should Apply
- Feasibility Study Methodology: A Comprehensive Framework for CRE Development and Acquisition Analysis
- DSCR in Feasibility Studies: The Complete Guide for Lenders, Developers, and Investors
- Sensitivity Analysis in Feasibility Studies: The Complete Guide for Lenders, Developers, and Investors
- Rationalizing the Development Budget: How a Feasibility Study Tests Project Cost Across Seven Asset Classes
- Rationalizing Operating Expenses Across Seven Asset Classes: Normalization, Benchmarks and Valuation for Lender-Grade Feasibility Studies (2026)
- Operating Expense Ratios and Cap Rates by Asset Class: The 2026 Benchmark Reference for Feasibility Studies and Valuation
- Hotel Feasibility Studies: When SBA Requires One, and Why the Pipeline Decides the Answer
- Going-Concern Allocation: The Two Numbers Holding It Up Are Both Market Studies
- Prospective Value: The Gap Between Two of Your Three Numbers Is a Feasibility Study
- How USDA Deducts Going-Concern Value From Collateral: Hotels, Gas Stations and Car Washes
- Hospitality Market Outlook for SBA Hotel Development
- U.S. Hotel Industry 2026: First RevPAR Decline Since 2020 Meets Record Pipeline
- Hotel Feasibility Study by Chain Scale: The 2026 U.S. Opportunity and Financeability Map